Fintechzoom How Much House Can I Afford - Calculate
Note: FintechZoom Pro is independent and not affiliated with, endorsed by or associated with FintechZoom.com or FintechZoom.io. "FintechZoom" in this title is the search term readers use, not a reference to that company. This guide is for information only, not financial advice.
How much house you can afford depends on your income, your existing debts (your debt-to-income ratio), your credit score, the down payment and closing costs you can cover, and the ongoing costs of owning a home, such as property taxes, insurance, PMI and maintenance. "FintechZoom how much house can I afford" is a common search from buyers who want a clear way to check their finances before house hunting. This guide walks through how to assess your finances, budget, understand mortgages and DTI, plan for upfront costs and weigh other factors such as job stability and an emergency fund. It is general information, not financial or mortgage advice.

Key points:
- Start with an honest review of your income, expenses, debts and savings before you look at homes.
- Lenders focus on your credit score, debt-to-income ratio (DTI) and down payment.
- Your real monthly cost includes property taxes, homeowners insurance, possibly PMI and HOA fees, not just principal and interest.
- Budget for closing costs, typically 2% to 5% of the loan amount, plus an emergency fund of 3 to 6 months' expenses.
- A qualified financial adviser or mortgage professional can help you turn these numbers into a plan.
Why is buying a house so challenging right now?
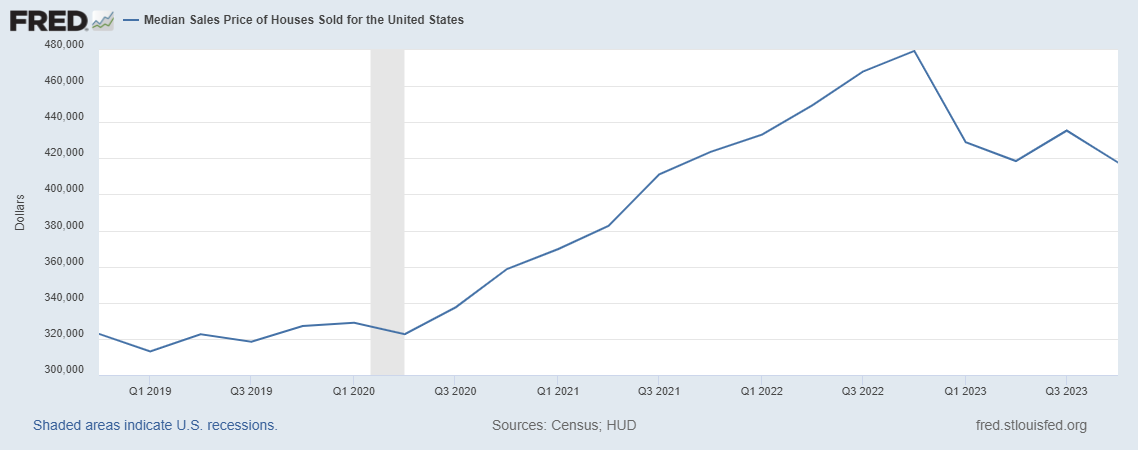
High house prices, inflation, changing mortgage rates and stricter lending rules have made homeownership harder to reach, especially for buyers without strong credit or steady income. Owning a home brings stability, security and the satisfaction of reaching an important milestone, but for many people it still feels out of reach. Even in large cities the market has become highly competitive.
Over the past few years, the US financial environment has been unpredictable, with frequent changes in mortgage and interest rates. Banks and lenders have set strict criteria for who can borrow, which makes it tough for some buyers to qualify.
What does "FintechZoom how much house can I afford" mean?
It is a search for help working out a realistic home budget; FintechZoom Pro answers it with an independent guide, not a lending service or personal calculator. FintechZoom Pro is an independent publication covering personal finance, banking, investing, crypto, fintech and market trends. It is not a lender, broker or credit service, and it is not affiliated with fintechzoom.com.
When you research a home purchase, the resources that help most are:
- educational guides on mortgages, credit and budgeting;
- housing market analysis for the areas you are considering;
- mortgage comparison tools from lenders or comparison sites;
- budgeting and affordability calculators;
- credit reports and credit monitoring from the credit bureaus or your bank;
- down payment assistance and loan programme information;
- advice from qualified professionals.
Related reading: FINTECHZOOM DIS STOCK – COMPETITIVE STOCK ANALYSIS OF WALT DISNEY.
How do you assess your financial situation before buying a house?
Work through ten areas: affordability, mortgage qualification, credit score, down payment, cash flow, loan approval, comparison shopping, risk, insurance and HOA fees, and PMI.
| Area | What to check |
|---|---|
| Affordability | Income, expenses, debts and savings; the maximum payment you can comfortably handle |
| Mortgage qualification | Lenders' credit score thresholds, DTI limits and down payment requirements |
| Credit score | Negative items you can fix to get a better rate |
| Down payment | Realistic savings goal and any assistance programmes |
| Cash flow | Ongoing costs of owning: taxes, insurance, maintenance, utilities |
| Loan approval | Income, debts and credit history lenders will review |
| Comparison shopping | Rates, terms and fees from several lenders |
| Risk management | Emergency fund, insurance and a contingency plan |
| Insurance and HOA | Homeowners insurance cost and any association fees |
| PMI | Extra monthly cost if you put down less than 20% |
1) How do you assess affordability?
Analyse your expenses, debts and savings to find the mortgage payment you can handle without straining your finances. A budgeting or mortgage affordability calculator can help you estimate a comfortable maximum payment and the price range it implies.
2) Can you meet mortgage qualification criteria?
Before applying, check whether you meet lenders' eligibility criteria, especially minimum credit scores, debt-to-income limits and down payment size. Understanding these requirements in advance lets you fix possible issues first and improves your chances of approval.
3) Why does your credit score matter?
Your credit score strongly affects the interest rate and terms you are offered. Identify and address any negative factors in your credit history before applying. A better score can help you qualify for lower rates, which can save thousands of dollars over the life of the loan.
4) How should you plan your down payment?
Set a realistic savings goal based on local prices and the loan type you want, and stick to a regular saving plan. Also research down payment assistance and alternative financing programmes, which can reduce how much you need to save up front.
5) How do you manage budgeting and cash flow as a homeowner?
Plan for every ongoing cost: mortgage payments, property taxes, insurance, maintenance and utilities. Managing cash flow carefully helps you avoid financial stress and stay stable as a homeowner.
6) What do lenders look at for loan approval?
Lenders assess your income, debts and credit history to decide whether to lend and on what terms. Understanding your own position first means there are fewer surprises when you apply.
7) Why should you comparison shop for a mortgage?
Different lenders offer different rates, terms and fees, so comparing several helps you find the most competitive deal for your goals. Use lender quotes and comparison tools to compare the full cost, not just the headline rate.
8) How do you manage the risks of buying a home?
Assess the risks honestly and build a contingency plan, such as an emergency fund and suitable insurance. Ask yourself: "Am I rushing into buying? Will this make it hard to live on my current income?" These questions can be uncomfortable, but they are far better than risking foreclosure. An emergency fund and the right insurance cover can protect you against job loss, illness or an economic downturn.
9) What are homeowners insurance and HOA fees?
Homeowners insurance protects the property and your liability and is normally required by mortgage lenders; HOA fees are charges for communities run by a homeowners' association.
- Homeowners insurance (HOI): property insurance covering losses and damage to your house and belongings, plus liability cover.
- HOA fees: monthly or annual charges if your property is in a community governed by a homeowners' association. They pay for maintaining common areas and shared facilities.
10) What is private mortgage insurance (PMI)?
PMI is insurance a borrower may have to pay for on a conventional loan when the down payment is less than 20% of the home's price. It protects the lender if you cannot repay the loan, and it increases your monthly payment, so include it when you work out how much house you can afford.
What are the budgeting basics for buying a home?
A home-buying budget rests on tracking income and expenses, setting goals, building a budget, managing debt, saving and reviewing your spending regularly. Budgeting apps, spreadsheets and your bank's tools can all help.
| Budget component | What it involves |
|---|---|
| Income tracking | Recording every source: salary, freelance work, rental income, investments |
| Expense tracking | Categorising spending such as housing, utilities, groceries and entertainment |
| Goal setting | SMART goals for a down payment, debt payoff, emergency fund or retirement |
| Budget creation | Allocating money to categories and setting spending limits |
| Debt management | Tracking balances and planning faster, cheaper payoff |
| Savings and investments | Automated saving towards specific goals |
| Expense analysis | Reviewing trends and reports to find adjustments |
| Alerts | Bill reminders and balance alerts to avoid missed payments |
1) Why track your income?
Budgeting starts with knowing your income and buying power. List every source, whether salary, freelance work, rental income or investments, to get a clear picture of your cash flow.
2) Why track your expenses?
Expense tracking shows where your money actually goes. Record and categorise all spending, such as housing, utilities, groceries and entertainment, so you can spot areas to cut back or where you need to allocate more.
3) How should you set financial goals?
Set specific, measurable, achievable, relevant and time-bound (SMART) goals. Examples include saving for a down payment, paying off debt, building an emergency fund or saving for retirement. Clear goals help you stay motivated and focused.
4) How do you create a budget?
Build a personalised budget from your income, expenses and goals. Allocate money to categories, set spending limits and track progress over time. Templates and automated budgeting apps can simplify the process.
5) How should you manage debt?
Track all your debts, such as credit cards, student loans and any existing mortgage, and plan how to reduce them. Debt payoff calculators, consolidation options and strategies to cut interest costs can help you pay off debt faster and improve your DTI.
6) How do savings and investments fit in?
Make saving a fixed part of your budget. Savings goal trackers and automatic transfers help you build separate pots for an emergency fund, holidays or retirement while you save for a home.
7) Why analyse your spending regularly?
Regular reviews reveal trends and changes in your spending. Reports and charts from budgeting tools help you identify where to adjust to improve your financial health.
8) Do alerts and notifications help?
Yes, alerts for upcoming bills, account balances and goal progress help you avoid overspending and missed payments. Most banks and budgeting apps offer them.
What role does a mortgage play in buying a home?
A mortgage is a loan secured on the property: you borrow a set amount to buy real estate and repay it with interest over an agreed term, and the lender can take the property if you default. Mortgage calculators show how much you might borrow and your likely monthly payments, and comparison tools show the products, terms and rates available.
What are the main types of mortgages?
The two basic types are fixed-rate and adjustable-rate mortgages.
| Type | How the rate works | Effect on payments |
|---|---|---|
| Fixed-rate mortgage | Same interest rate for the whole term | Predictable payments |
| Adjustable-rate mortgage (ARM) | Rate can change with market conditions | Payments can rise or fall over time |
How do interest rates and terms affect your payments?
A lower interest rate means lower monthly payments and less interest overall, while the term (often 15, 20 or 30 years) sets how quickly you repay and how much interest builds up. Shorter terms usually mean higher monthly payments but less total interest. Mortgage calculators let you test different amounts, rates and terms, and show how extra payments can shorten the loan and reduce total interest.
What should you include when calculating monthly payments?
Include property taxes, homeowners insurance and, if your down payment is under 20%, PMI on top of principal and interest. These costs add to what you pay each month. Understanding every element helps you manage your finances and choose the mortgage that best fits your needs.
What is the debt-to-income ratio (DTI)?
Your debt-to-income ratio is the percentage of your gross monthly income that goes to debt payments: total monthly debt payments divided by gross monthly income, multiplied by 100.
- Debt payments include: mortgage or rent, minimum credit card payments, car loans, student loans, alimony, child support and other ongoing debt obligations.
- Gross monthly income: your total income before taxes and other deductions.
- Example: $2,000 of monthly debt payments on a $6,000 gross monthly income gives a DTI of about 33%.
The lower the percentage, the healthier your finances look. Lenders use DTI in underwriting to judge your ability to manage monthly payments and the risk of lending to you, so a lower DTI makes it easier to get a loan.
Why does DTI matter when buying a house?
Lenders prefer borrowers with a lower DTI because less of their income is already committed to debt, leaving more room for a mortgage payment and other costs. A lower DTI signals financial stability and lowers the lender's default risk, which can make it easier to qualify and to secure better interest rates.
How much do you need for a down payment and closing costs?
You need cash for both the down payment and closing costs, which typically range from 2% to 5% of the loan amount. Understanding both before you start helps you budget for the upfront costs of buying.
| Upfront cost | What it is | Typical size |
|---|---|---|
| Down payment | Your upfront share of the purchase price | Varies by loan; 20% avoids PMI on a conventional loan |
| Closing costs | Fees for finalising the mortgage and transferring ownership | Typically 2% to 5% of the loan amount |
Why does the size of your down payment matter?
A larger down payment reduces the loan amount and the lender's risk, which can lead to more favorable mortgage terms, such as a lower interest rate and smaller monthly payments. It also shows financial responsibility. The right amount depends on your savings, the loan type and how much cash you want to keep in reserve.
What do closing costs include?
Closing costs cover loan origination fees, appraisal fees, title insurance, attorney fees and prepaid items such as homeowners insurance and property taxes. They vary by location, loan type and lender. Compare lenders' loan estimates and ask which fees can be negotiated or reduced.
How can you save for a down payment and closing costs?
Automate your saving and keep the money somewhere safe that earns interest.
- Set up monthly automatic transfers from your checking account to a dedicated savings account.
- Consider high-yield savings accounts or certificates of deposit (CDs) to earn more interest while you save.
- Match the savings vehicle to your timeline so the money is available when you need it.
Planning for these costs helps you cover home-buying expenses and secure a mortgage that fits your long-term goals.
What other factors affect how much house you can afford?
Job stability, your long-term financial goals, the economy and the size of your emergency fund all matter alongside the mortgage numbers.
1) How stable is your job and future income?
A mortgage is a long-term commitment, so assess how secure your income is and how it may grow. Review your career path, industry trends and local job market. Exploring additional income streams or career advancement can strengthen your financial security over time.
2) How does buying fit your long-term goals?
Make sure homeownership supports, rather than undermines, goals such as retirement saving, your children's education or starting a business. Prioritising these goals helps you decide when and how to buy.
3) Which economic factors should you watch?
GDP growth, inflation, unemployment, interest rates and local housing trends all affect affordability. Staying informed about these indicators and local market conditions helps you anticipate risks and opportunities and think about the timing of your purchase.
4) How big should your emergency fund be?
A common guideline is an emergency fund covering 3 to 6 months of living expenses. It is a safety net for home repairs, medical bills or job loss, so an unexpected cost does not threaten your mortgage payments. Build it before you buy and keep it topped up afterwards.
Should you get professional advice before buying a home?
Yes, especially if you are a first-time buyer; a qualified financial adviser or mortgage professional can review your finances and help you set a realistic budget. Advisers can spot areas to improve and suggest ways to strengthen your finances, including handling debt, improving your credit score, saving, investing and tax planning. They can also help with complicated choices about budgeting and choosing a mortgage.
What should you expect from a consultation?
Expect a detailed discussion of your finances and home-buying goals, so prepare your documents in advance.
- Bring: pay stubs, tax returns, bank statements and credit reports.
- Expect questions about: your income and spending, priorities, risk tolerance and when you want to buy.
- Be open: honest, complete information lets the adviser tailor recommendations to your needs.
- Follow through: sticking to the agreed plan improves your chances of buying a home you can comfortably afford.
Key takeaways
- Work out affordability from your full financial picture: income, debts, credit, savings and ongoing homeowner costs.
- Keep your DTI low and your credit score strong to qualify for better terms.
- Budget for the down payment, closing costs of roughly 2% to 5% of the loan, PMI if you put down under 20%, insurance and HOA fees.
- Keep 3 to 6 months of expenses in an emergency fund and consider job stability and long-term goals.
- Use calculators for estimates and a qualified professional for personal advice.
How much house can I afford FAQs
Is FintechZoom Pro's advice personalised to my financial situation?
No. FintechZoom Pro is an independent publication that provides general information. For advice based on your circumstances, speak to a qualified financial adviser or mortgage professional.
Are there any fees for using FintechZoom Pro?
Our guides are free to read. FintechZoom Pro does not offer loans, mortgages or credit services, and it is not affiliated with fintechzoom.com.
What should my down payment be for a $300,000 house in Canada?
The minimum is 5% of the first $500,000 of the price, so $15,000 on a $300,000 home. With less than 20% down you must pay mortgage default insurance, so 20% ($60,000) avoids it. Check current rules with a lender.
How does the debt-to-income ratio affect my mortgage qualification?
Your DTI is a key factor in mortgage approval. A low DTI shows lenders you can comfortably manage a mortgage payment alongside your other debts, which can improve your chances and your terms.
What is included in the mortgage stress test in Canada?
The stress test checks that you could afford payments at a qualifying rate higher than your actual contract rate, generally the greater of your contract rate plus 2 percentage points or 5.25%.