Modern Cash Flow Depends on Smarter Infrastructure
Cash flow now moves at the speed of payment infrastructure. A business may record strong sales and still face a short-term funding gap if customer payments take several days to settle. Faster rails, automated reconciliation and clearer transaction data can shorten that delay, but each improvement also creates new operational questions. Finance teams need to understand when funds become available, where exceptions occur, and which providers can support growth without introducing hidden costs or concentrated risk.
Real-Time Settlement Demands
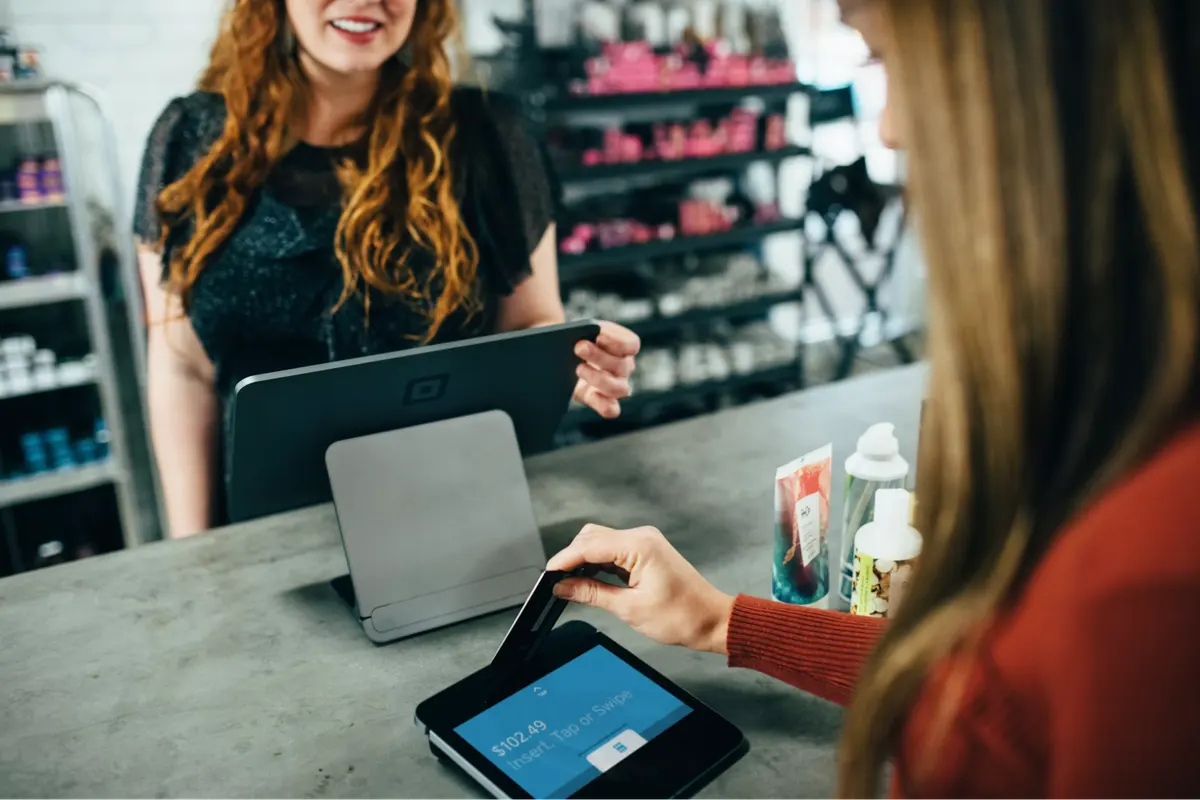
Customers increasingly expect immediate confirmation, while businesses want equally fast access to funds. The growth of real-time payment rails is pushing treasury teams to monitor liquidity beyond traditional banking hours.
Fast settlement can help a retailer restock popular products after a strong weekend or allow a service company to pay contractors sooner. Still, instant movement requires accurate account balances and dependable fraud controls. Map when each payment type becomes usable cash, including weekends and holidays. Then set alerts for unusual volumes, failed transfers, and settlement delays so staff can respond before a timing issue affects payroll or supplier payments.
Where Friction Slows Working Capital
Payment friction often hides between a completed sale and a reconciled bank deposit. Batch schedules, manual invoice matching, chargeback reviews, and data errors can each delay access to working capital.
For example, a company processing 500 daily orders may receive one combined deposit that lacks usable order references. Employees then spend hours matching transactions before finance can trust the balance. Industry guidance on cash flow challenges highlights how connected financial tools can reduce these gaps. Track settlement time by payment channel and record exception rates. A channel that settles quickly but creates frequent manual corrections may still impose a high operational cost.
How to Vet Modern Payment Processors
Evaluate payment processors against your actual transaction pattern, including average order value, peak volume, and sales channels. Request a complete fee schedule covering setup, monthly service, transactions, disputes, and early termination.
Ask candidates to demonstrate reporting, refunds, and deposit reconciliation using sample transactions. Confirm their normal settlement windows and procedures for delayed or held funds. Integration quality also matters. A provider should connect cleanly with your checkout, accounting platform, and fraud tools. If your company needs multiple providers or payment routes, understanding payment orchestration versus a payment processor can clarify which infrastructure model fits the operation.
Mitigating Merchant Risk in Automation
Automation can approve payments, issue refunds, and update ledgers within seconds, so poorly designed rules can multiply errors just as quickly. Start with clear limits for transaction value, refund frequency, and repeated payment attempts.
Keep human approval for unusual cases, such as a refund above a set amount or a sudden increase in transactions from one account. Access controls should separate who creates an automation rule from who approves it. Maintain logs that show each action, timestamp, and system response. Teams should test rule changes in a sandbox before release, then review outcomes after 24 hours and again after one week. A documented manual process is also necessary when an integration fails.
Building a Resilient Treasury Stack
A resilient treasury stack gives finance teams more than one way to receive data, confirm balances, and move funds. Connect payment records with accounting and cash forecasting systems, but avoid making one dashboard the only source of truth. Daily bank confirmations can expose missing or duplicated entries.
Define ownership for every integration and maintain current contact details for provider support. Set practical recovery targets, such as restoring transaction reporting within two hours and completing reconciliation before the next business day. Quarterly drills can reveal expired credentials, broken alerts, or undocumented dependencies. The strongest final test is simple: finance should be able to identify available cash, pending settlements, and unresolved exceptions from a single operating view.